
Perth-based · 40+ lenders · Australia-wide
Greenside Finance team · Updated November 2026
A chattel mortgage is a business loan to buy a vehicle or equipment: your business owns the asset from day one and the lender holds it as security until the loan is paid. Greenside Finance is a Perth-based chattel mortgage broker comparing 40+ lenders for ABN holders in Western Australia, and we lend Australia-wide. Getting a quote is free.
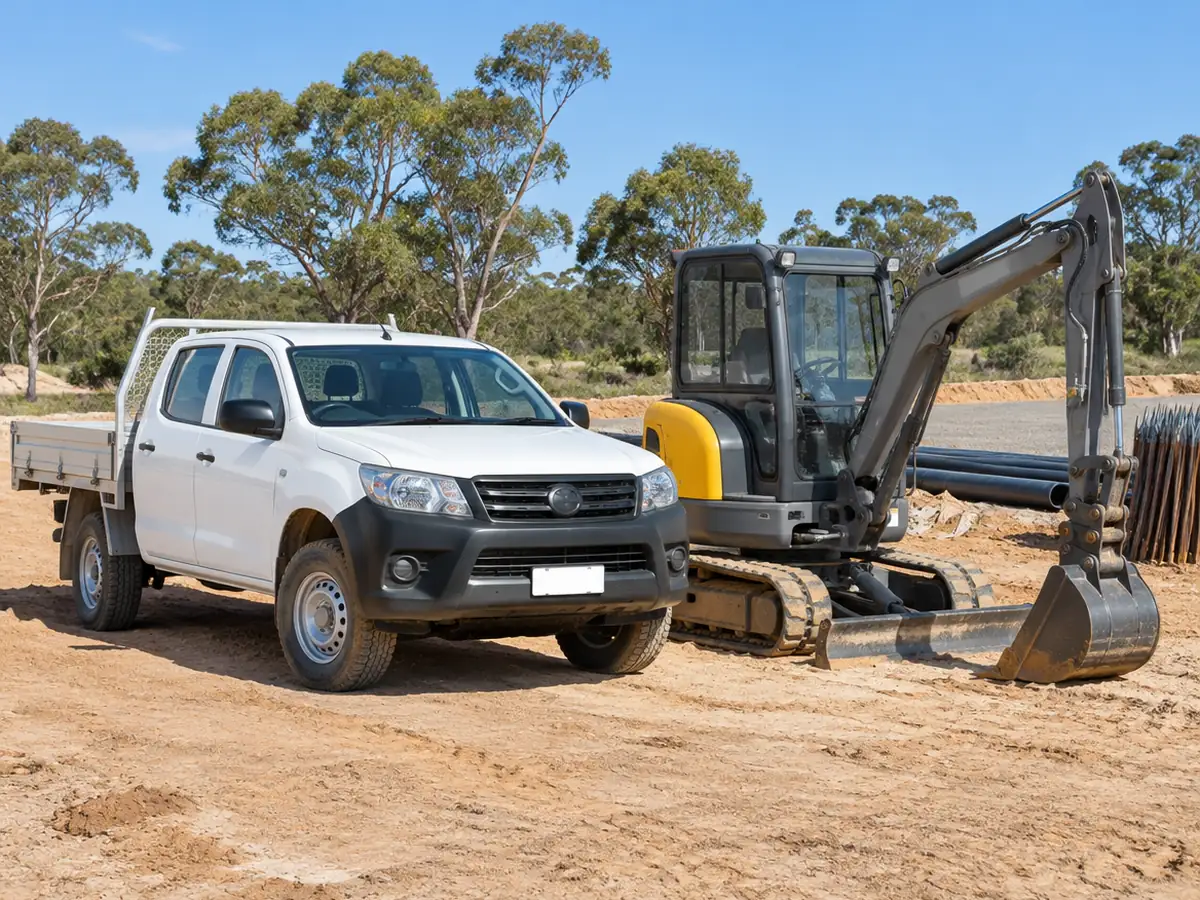
Greenside Finance is a Perth-based finance brokerage at Unit 5/531 Hay St, Subiaco WA 6008. We arrange chattel mortgages for sole traders, companies and trusts buying cars, utes, vans, trucks, trailers and equipment, and we lend Australia-wide. You deal with a named broker: Tom Dihm, James Brynjulfsen or Reolan Naidoo, by phone, email or in person at the office.
Our Google rating is Excellent from 82 reviews (as at October 2026). Read them yourself before you choose any broker, ours included.
The best broker for you is one who compares many lenders, explains the structure in plain words and puts the options in writing. Ask every broker, us included, these questions:
With a chattel mortgage the lender pays the seller, your business owns the vehicle or equipment straight away, and you repay the lender over a set term, usually one to seven years. The lender registers its security on the PPSR and releases it when the loan is paid out. Repayments are fixed, and you can add a balloon (a final payment) to lower them. It is the most common way ABN holders finance work vehicles and equipment.
| Option | Who owns the asset | Usually suits |
|---|---|---|
| Chattel mortgage | Your business, from day one | ABN holders buying a vehicle or equipment for the business, especially if GST-registered. A balloon can lower repayments. |
| Finance lease | The lender, until the end of the lease | Businesses that prefer to lease. At the end you pay out the residual, refinance or trade in. GST is generally spread across the payments. |
| Rental (operating lease) | The lender, and you hand it back | Equipment you expect to swap often or don't want to own. |
| Commercial hire purchase | The lender, until the last payment | Now rare. Since 2012 its GST treatment has matched a chattel mortgage, so most lenders simply write chattel mortgages. |
| Consumer car loan | You, from day one | Buyers using the car mainly for personal use. See car loans. |
Which one suits you depends on your cash flow, GST status and tax position, so confirm the choice with your accountant. We arrange chattel mortgages and leases; we don't arrange novated leases.
This is general information, not tax advice, and we are not tax agents, so talk to your accountant about your own situation.
A balloon, also called a residual, is a final payment you defer to the end of the term to lower your repayments. Balloons are usually available on newer assets, and they usually get smaller as the term gets longer, with none at many lenders on the longest terms. At the end you pay it, refinance it or sell or trade in the asset to cover it. A balloon lowers your repayments but means a lump sum later, so we quote it with and without.
| Option | What it needs |
|---|---|
| Low doc | ID and your self-declared income. No full financials or tax returns needed. Lenders choose which low doc loans they offer, usually to established businesses. |
| Lite doc (easy doc or mid doc) | Recent BAS or business bank statements instead of tax returns. Its own option, for businesses that prefer it or whose ABN is newer. |
| Full doc | Tax returns or financials and notices of assessment. Often used for larger amounts and multi-asset deals. |
Whichever you use, also have your driver's licence, ABN and GST details, and the dealer invoice or private sale details. See low doc loans for more.
| Factor | What it means for you |
|---|---|
| ABN and GST age | A smaller group of lenders from a new ABN, more from 12 months, and the widest choice from around 2 to 3 years of ABN and 1 or more years of GST. |
| Property | Owning property often opens more lenders and can allow the full price to be financed. |
| Deposit | Often none for established ABNs and property owners. Without property, many lenders ask for 10 to 20%. |
| Asset type and age | Trucks, utes, vans and yellow goods are the easiest to fund, and most cars too. Lenders look at the asset's age at the end of the loan. |
| Credit history | A good credit history opens the panel. Past defaults narrow the choice of lenders, but they don't always rule you out. |
You can usually pay a chattel mortgage out early, for example if you sell or upgrade the asset. Most lenders charge an early exit (break) cost, and how it is worked out varies a lot between lenders and between loans, often being higher in the early years. If you expect to sell or upgrade within a few years, tell us at the start so we can favour lenders with lower break costs and explain in writing how each lender's exit cost is worked out.
A quote and a conversation cost nothing. The lender usually pays us a commission when a loan settles, and we explain any fees before you go ahead. We don't quote rates on this page because they depend on your business, the asset and the lender.
No. We are based in Subiaco, Perth, and we arrange chattel mortgages across Western Australia and Australia-wide. You are welcome at the office if you'd rather meet.
Choose a broker who is licensed, compares many lenders, explains balloons and exit costs and gives you the options in writing. Greenside Finance is a Perth-based broker comparing 40+ lenders, with a named broker from first call to settlement. Check the licence, ask the questions above, and read the reviews of any broker you consider.
Getting a quote is free. If your loan goes ahead, the lender usually pays us a commission, and we may also charge a brokerage (origination) fee. Any fee is only charged if your loan settles. It is added to your loan amount, so it forms part of your repayments, and it is never paid upfront. We'll explain any fees before you go ahead. Our credit guide explains how our fees and commissions work.
No. Our brokerage fee is never paid upfront. If a fee applies, it is added to your loan and shown in your quote before you sign.
With a chattel mortgage your business owns the asset from day one and the lender holds it as security. With a lease the lender owns it and you pay to use it, usually with a residual or an option to buy at the end. Check which suits your tax position with your accountant.
If you're GST-registered, you may be able to claim the GST on the purchase price in your BAS. This is general information, not tax advice, and we are not tax agents, so confirm with your accountant.
It can apply to eligible assets costing under $20,000 for small businesses. For dearer assets, depreciation applies instead. Confirm with your accountant.
Often, yes, on newer assets. A balloon lowers repayments but leaves a lump sum at the end, so we quote it with and without. Balloons usually get smaller on longer terms.
Often, yes. Low doc needs ID and your self-declared income, with no full financials or tax returns, and lenders choose which low doc loans they offer. If you can supply BAS or business bank statements, that opens a lite doc option as well. See low doc loans.
Sometimes. A smaller group of lenders accept a newer ABN, often with a deposit and experience in the same trade, and the choice improves at 12 months and again at around 2 years. Tell us your ABN and GST dates and we will say which lenders are open to you.
Usually, yes, but most lenders charge an early exit cost and it varies between lenders. Tell us if you expect to sell or upgrade within a few years so we can pick lenders with lower break costs.
No. Getting a quote has no impact on your credit score. A credit enquiry is only listed on your file if you go ahead with a formal application, and we tell you before that happens.
Two quick steps. Getting a quote won’t affect your credit score.
Greenside Finance Pty Ltd (ABN 76 678 053 122) is an Authorised Credit Representative (#561052) of Fintelligence Pty Ltd, Australian Credit Licence #511803. Unit 5/531 Hay St, Subiaco WA 6008 · 1800 147 336. All finance is subject to lender approval, terms, conditions and fees. Information on this page is general and doesn't consider your objectives, financial situation or needs.

