
Perth-based · 40+ lenders · Australia-wide
Greenside Finance team · Updated October 2026
Finance for a new or used ute, for work or personal use. A Perth broker compares 40+ lenders for you, Australia-wide.
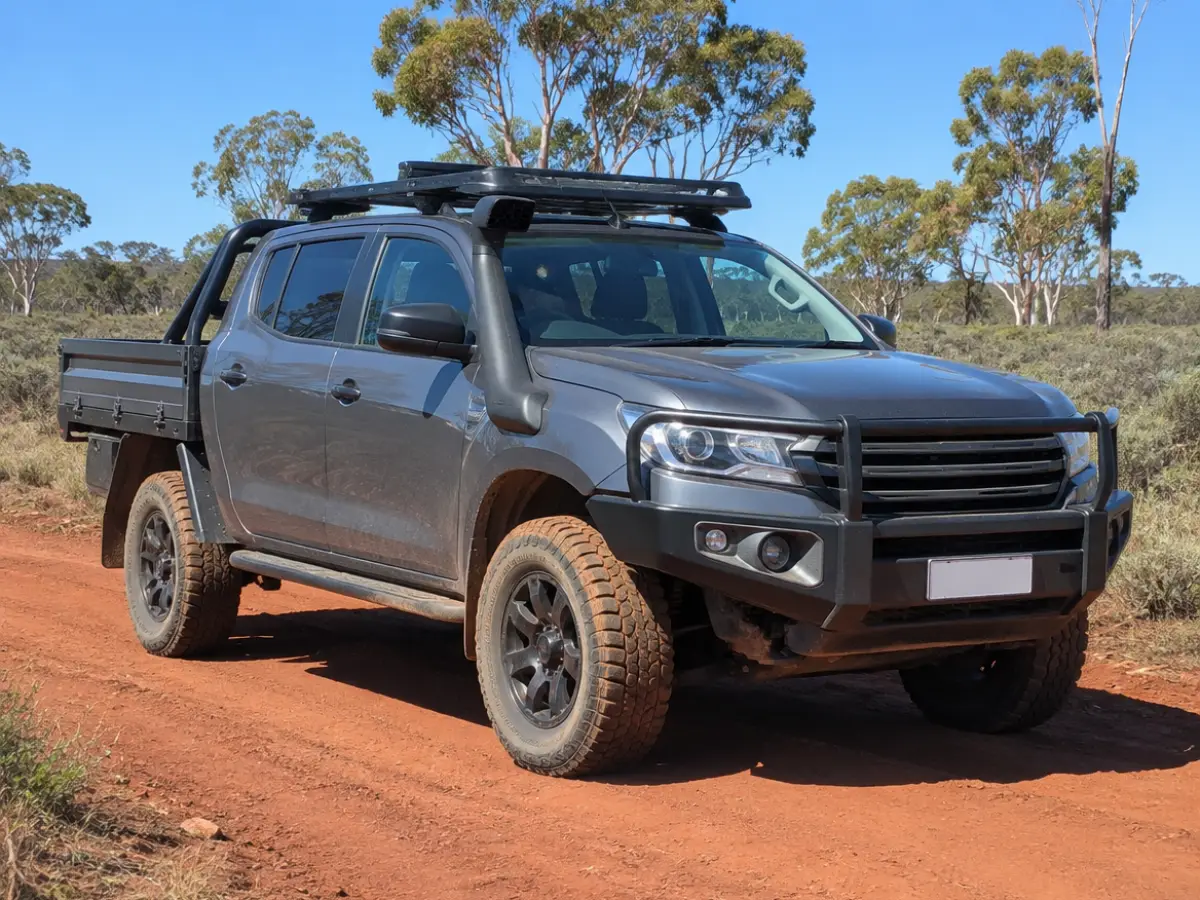
Ute finance is a loan to buy a new or used ute from a dealer, at auction or from a private seller. If you have an ABN and use the ute mainly for business, it's usually a chattel mortgage: you own the ute from day one, the lender holds it as security, and the fit-out can go on the same loan. If the ute is mainly for personal use, it's a consumer car loan. Greenside Finance is a Perth-based broker comparing 40+ lenders for both, across Western Australia and Australia-wide.
The ute and the fit-out bought with it: tray, canopy, drawers, tool boxes, racks, towbar, and mine-spec gear such as light bars, buggy whip, flags, UHF, beacons and roll-over protection. Lenders cap accessories at a share of the vehicle's value, so we check the build sheet against the lender before you sign. Gear added later by a separate supplier is harder to include.
Box trailers, tradie and tool trailers, tandem and plant trailers for business use. Buying one with the ute? It can often go on the same loan, itemised on the invoice. Buying it on its own, or from a separate trailer maker? It can be its own business loan, and smaller amounts are fine. The same lender checks apply: ABN, the seller's invoice and what the trailer is for.
| Factor | What it means for you |
|---|---|
| ABN age | Some lenders accept a new ABN if you've worked in the same trade, usually with a deposit. More open up at 6 and 12 months. The widest choice usually starts around 2 years. An older sole-trader ABN can often count when you move to a Pty Ltd. |
| GST registration | Many lenders want 12 months or more for their top tiers. Not being registered can cap the loan size at some lenders. |
| Property | Owning a home (a spouse's name counts at some lenders) is the biggest lever: easier no-deposit and low doc approvals. |
| Deposit | Without property, many lenders want 10–20% as cash or trade-in. A few lend with no deposit, at a higher cost. |
| Credit | A good credit history with repayment history opens the panel. Defaults and lots of recent enquiries narrow it. |
| Where you live | Some lenders exclude parts of the Goldfields, Pilbara and Kimberley by postcode. We check before quoting. |
Buying the ute for personal use? Lenders look at your income and job, your living expenses, your credit history and any deposit or trade-in, rather than ABN and GST.
Personal use (consumer car loan): driver's licence, recent payslips, bank statements and the details of the ute.
Business, low doc:
Business, lite doc (easy doc or mid doc): recent BAS or business bank statements instead of tax returns, for businesses that don't meet low doc criteria.
Business, full doc: your last two years' tax returns or financials and ATO notices of assessment.
Low doc suits established ABN holders whose tax returns aren't up to date: the lender relies on your declared income, without full financials or tax returns. It suits businesses with about 2 years of ABN, GST registration and property, and a few lenders offer it from 12 months of ABN and 6 months of GST with lower loan limits. Lite doc uses BAS or bank statements and suits newer ABNs or non-owners. Full doc uses tax returns or financials. Rates depend on the lender and your profile; low doc is often priced the same as full doc for established businesses. For most tradies, low doc is the first thing we check. More detail: low doc loans.
For a ute used mainly for business, most tradies use a chattel mortgage: you own the ute from day one and the lender holds it as security. A lease suits some businesses that prefer the lender to own the vehicle. If the ute is mainly for personal use, it's a consumer car loan instead. This is general information, not tax advice: your accountant can tell you which structure suits your tax position.
| Option | Who owns the ute | Usually suits |
|---|---|---|
| Chattel mortgage | You, from day one | ABN holders using the ute mainly for business; a balloon can lower repayments |
| Finance lease | The lender, until the end of the lease | Businesses that prefer to lease; at the end you pay out, refinance or trade in against the residual |
| Consumer car loan | You | Employees buying a ute mainly for personal use. We arrange these too |
Comparing brokers for a chattel mortgage? See how to choose a chattel mortgage broker in Perth.
Illustrative scenario based on common enquiries, not a specific client. An electrician in Perth's northern suburbs, renting, ABN about 18 months old and GST-registered for 12, wanted a used dual-cab with a tray and canopy for around $60,000, with no deposit. With no property and an ABN under two years, no deposit narrowed the field to a few lenders at a higher cost. Putting the old ute in as a trade-in opened more of the panel, and the canopy went on the same invoice so it could be financed with the vehicle.
Yes. If the ute is mainly for personal use, such as weekends away, towing or getting to work, it's a consumer car loan, assessed on your income, expenses and credit history. You don't need an ABN. We compare 40+ lenders for these too.
Yes. Some lenders accept a new ABN, especially if you've done the same work before as an employee. Expect fewer choices and a request for a deposit or property backing until your ABN reaches 12–24 months.
Not always. Property owners and established ABN holders can often finance the full price. Without property, many lenders ask for 10–20% in cash or trade-in.
Usually, if they're bought with the ute and itemised on the invoice, within the lender's accessory limit. Mine-spec fit-outs are treated the same way.
Yes, for business use. A trailer bought with the ute can often go on the same loan; a trailer bought separately can be its own loan, including smaller amounts. See trailer finance above.
Yes. Many lenders fund private and auction purchases; a few are dealer-only and some price private sales higher. We run a PPSR check at no cost to you, any finance owing is paid out, and the lender pays the seller directly. In WA the transfer goes through the Department of Transport and Major Infrastructure (DTMI), where the buyer pays vehicle licence duty. More on private sale car loans.
For most ABN holders using the ute mainly for business, yes: you own it from day one and the lender holds it as security. A lease or a consumer loan suits some buyers better. We explain the options and your accountant confirms the tax side.
If you're GST-registered and use a chattel mortgage, you may be able to claim the GST on the purchase price in your BAS. A car limit applies to some vehicles, including some dual-cabs. This is general information, not tax advice: check with your accountant.
Yes. Everything is done by phone, email and electronic signing. Some lenders exclude parts of regional WA by postcode, so we check yours before recommending a lender.
No. We're based in Subiaco, Perth, and arrange ute finance across Western Australia and Australia-wide. Most clients never need to visit the office: quotes, documents and signing are all done online or by phone.
Tell us up front. Break costs for paying out a business loan early vary widely between lenders, so it changes which lender suits you.
Two quick steps. No impact on your credit score to get a quote.
Greenside Finance Pty Ltd (ABN 76 678 053 122) is an Authorised Credit Representative (#561052) of Fintelligence Pty Ltd, Australian Credit Licence #511803. Unit 5/531 Hay St, Subiaco WA 6008 · 1800 147 336. All finance is subject to lender approval, terms, conditions and fees. Information on this page is general and doesn't consider your objectives, financial situation or needs.

