
Perth-based · 40+ lenders · Australia-wide
Greenside Finance team · Updated November 2026
Finance for new or used machinery, trucks, farm and workshop equipment, for ABN holders. A Perth broker compares 40+ lenders, Australia-wide.
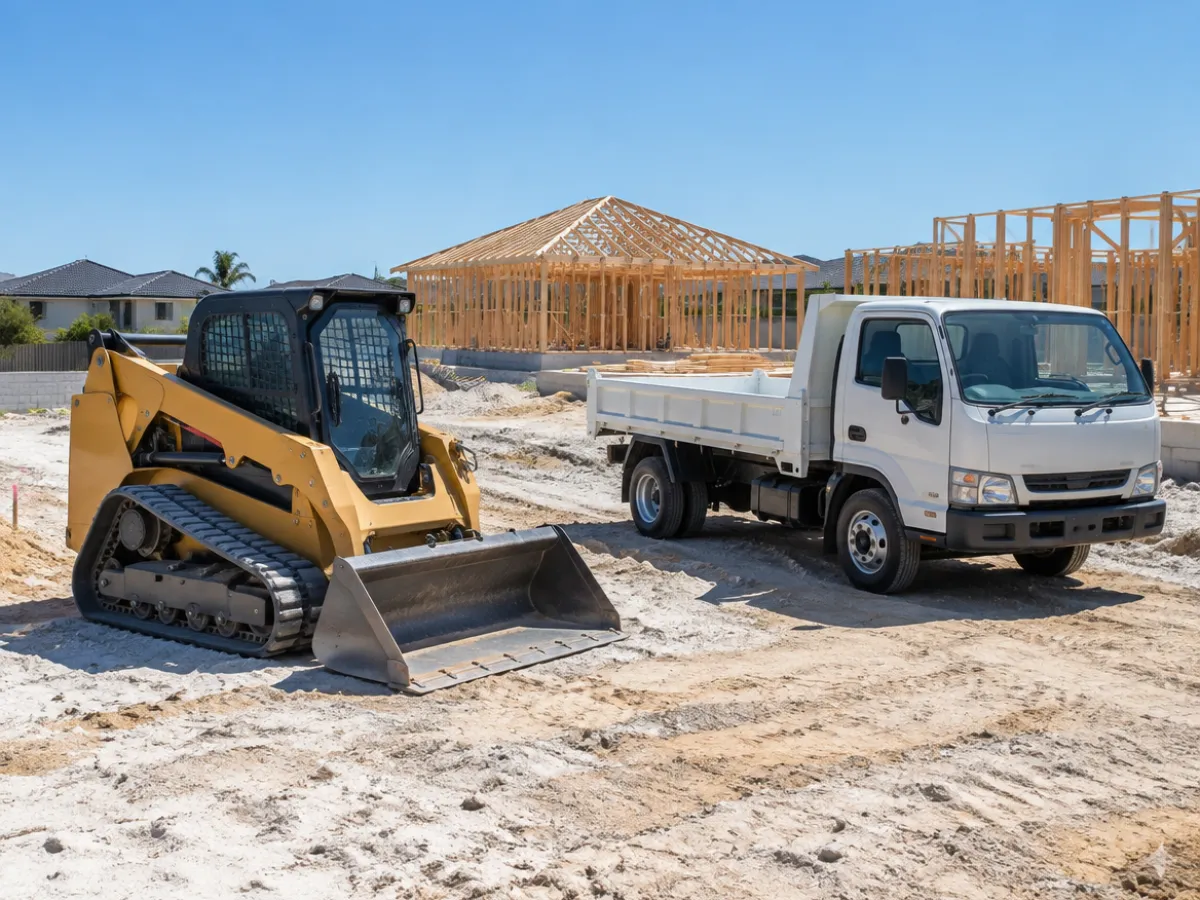
Greenside Finance arranges commercial equipment finance for ABN holders, companies and trusts: excavators, trucks, trailers, loaders, forklifts, farm and workshop equipment, new or used, from a dealer or a private seller. We're Perth-based finance brokers comparing 40+ lenders on a chattel mortgage, finance lease, rental or low doc equipment loan, and we lend across Western Australia and Australia-wide.
| Asset | Notes |
|---|---|
| Excavators, loaders, skid steers and other yellow goods | Dozers, graders, rollers, backhoes, attachments. See excavator finance. |
| Trucks, prime movers and trailers | Rigid trucks, tippers, tray trucks, semi-trailers. See truck finance and choosing a truck finance broker. |
| Forklifts and material handling | Forklifts, work platforms, cranes and pallet equipment. |
| Agricultural machinery | Tractors, headers, seeders, sprayers. Some lenders also fund primary producers. |
| Workshop, manufacturing and fit-out equipment | Lenders treat these as secondary assets, so age limits are tighter and a deposit is more common. |
| Medical and hospitality equipment | Case by case. Some lenders take it and a few exclude the industry, so we check before quoting. |
| Work utes and vans | See ute finance for tradies and ABN holders and business car loans. |
Minimum loan amount is generally $10,000. Used equipment and private sales are fundable at many lenders, subject to age, condition and value. We finance equipment for construction, civil, earthmoving, transport, mining services, agricultural and trade businesses across WA, from Perth to the Pilbara, Goldfields, Wheatbelt and South West, and for operators interstate.
| Option | How it works | Suits |
|---|---|---|
| Chattel mortgage | Your business owns the equipment from day one and the lender holds it as security. GST-registered businesses may be able to claim the GST on the purchase price in the next BAS. Interest and depreciation may be deductible. | Most GST-registered businesses. The usual starting point. |
| Finance lease | The lender owns the equipment and you pay to use it, with a residual or an option to buy at the end. GST is generally spread across the payments. | Equipment you may want to return or upgrade, or lower repayments with a residual. |
| Rental (operating lease) | You rent the equipment for a set period and hand it back or renegotiate. Available on some assets and from some lenders only. | Short-term needs, fast-changing technology, or keeping the asset off your balance sheet. |
Comparing brokers for a chattel mortgage? See how to choose a chattel mortgage broker in Perth.
Commercial hire purchase is now rare: since 2012 its GST treatment has matched a chattel mortgage, so most lenders simply write chattel mortgages. Which option suits you depends on cash flow, GST status and tax. Confirm it with your accountant; we'll lay the options side by side.
| Feature | What's usually available |
|---|---|
| Loan amount | From $10,000. Low doc (no full financials or tax returns) commonly to $100,000 to $250,000, and to about $400,000 at a few lenders for property-backed businesses with a good credit history and a comparable loan paid on time. Lite doc (BAS or bank statements) to about $500,000 at some lenders. Larger amounts and fleet facilities on full financials. |
| Term | 1 to 5 years standard; up to 7 years on primary assets such as trucks and earthmoving at several lenders. Older equipment usually means a shorter maximum term. |
| Balloon (residual) | Typically up to 40 to 50% on a 3 year term, 35 to 45% on 4 years and 30 to 35% on 5 years; none on terms over 5 years at most lenders. Balloons are usually limited to newer primary assets. |
| Deposit | Often none for property owners and established ABNs (100% of the invoice, including GST, can be financed). Without property, expect 10 to 20%. |
| Repayments | Monthly is standard; some lenders offer seasonal or quarterly schedules for agricultural and contracting businesses. |
| Approval time | Straightforward low doc applications on common assets are often decided the same day, sometimes within hours. Full doc and larger deals usually take 1 to 3 business days. Approval always depends on the lender's assessment. |
The government's instant asset write-off lets eligible small businesses deduct the cost of an asset costing under $20,000 in the year it's first used or installed. It's permanent from 1 July 2026 for businesses with turnover under $10 million. Eligibility and timing depend on your situation, so confirm with your accountant. See the ATO's instant asset write-off page.
| Factor | What it means for you |
|---|---|
| ABN age | Some lenders accept an ABN of 3 to 12 months, usually with a deposit. The widest choice starts at about 2 years, and the sharpest tiers at 3 years or more. |
| GST registration | Top tiers usually want 1 to 3 years of GST registration. An older ABN can often be counted when you move from sole trader to company. |
| Property | Owning a home (a spouse's name counts at some lenders) is the biggest lever for low doc approval and a better price. |
| Deposit | Without property, many lenders want 10 to 20%. Some lend with no deposit at a higher cost. |
| The equipment | New and common equipment is easiest. Lenders grade assets: primary (trucks, trailers, earthmoving, ag machinery, forklifts) are usually up to about 15 to 20 years old at the end of the loan, and a few lenders go to 25; secondary (workshop, machining, manufacturing plant) about 10 to 15 years; tertiary (IT, fit-out, medical, hospitality) 5 to 10 years and often new only, with a deposit and a higher rate. |
| Credit | A good credit history gives you the most lender choice. Past defaults or lots of recent enquiries narrow the options but don't always rule you out. |
Tradies can finance tools, trailers, skid steers, mini excavators and other work equipment through Greenside Finance, a Perth-based broker that compares 40+ lenders and arranges finance Australia-wide, including across Western Australia. These are business loans, so you need an ABN and the equipment must be mainly for business use. Some lenders will consider an ABN of a few months, others want 12 to 24 months, and low doc options rely on your declared income instead of full financials or tax returns. Need a work ute or van? See ute finance, or read how a chattel mortgage works. Get a free quote.
Have these ready and most applications can be lodged the same day. Low doc:
Lite doc (easy doc or mid doc): as for low doc, plus recent BAS or business bank statements. It suits businesses that don't meet low doc criteria.
Full doc: two years of tax returns or financials. See low doc and lite doc loans for who qualifies. Need working capital alongside the equipment, such as an overdraft or an equipment line? See business funding.
Anonymised from a real file.
A drainage contractor bought two excavators privately from another business. The machines still had a security interest registered by the manufacturer's finance company. We ran the PPSR search the day the deal was quoted, because settlement could not go ahead until the manufacturer formally discharged its interest and a statutory declaration was completed. Starting the discharge early kept the purchase on schedule.
It's a loan or lease that lets a business buy equipment and pay it off over time, with the equipment as security. It keeps working capital free and lets the equipment earn while you pay for it.
Machinery, trucks and trailers, forklifts, farm and workshop equipment, and some fit-out and medical or hospitality equipment. Check our excavator finance and truck finance pages for detail on those assets.
Yes. Many lenders fund used equipment and private sales, subject to age, condition and value. A few are dealer-only. Tell us what you're looking at and we'll confirm which lenders will fund it.
With a chattel mortgage your business owns the equipment from day one. With a finance lease the lender owns it and you pay to use it, with the option to buy at the end. See the table above and check with your accountant.
Not always. Property owners and established ABN holders can often finance the full price. Without property, many lenders ask for 10 to 20%.
No. Our brokerage fee is never paid upfront. If a fee applies, it is added to your loan and shown in your quote before you sign.
Primary assets such as trucks, trailers and earthmoving are usually up to about 15 to 20 years old by the end of the loan, and a few lenders go to 25; workshop and fit-out equipment less. Older equipment may still be possible with a shorter term or a deposit.
It can apply to eligible assets costing under $20,000 for small businesses. For larger assets, depreciation applies instead. This is general information, not tax advice: confirm with your accountant.
Yes, but most lenders charge an early exit fee, and the amount varies widely between lenders. Tell us if you expect to sell or upgrade within a few years so we can pick a lender with low break costs.
Often, yes. Some lenders accept an ABN of 3 to 12 months with a 20% deposit, experience in the same trade and bank statements showing the business can service the loan, usually capped around $100,000 to $150,000. One or two have no minimum ABN age at all, to about $100,000. Choice and pricing improve at 12 months and again at 2 years.
Sometimes. A few specialist lenders fund equipment for businesses with past defaults or a discharged bankruptcy, usually with a deposit, a newer asset and a higher rate. A good credit history gives the widest choice; past problems narrow it without always ruling you out.
Yes, and it's the usual starting point for established businesses. With about 2 years of ABN and GST, property or a deposit, and a good credit history, many lenders will fund equipment on low doc, relying on your declaration of income instead of full financials or tax returns, commonly to $100,000 to $250,000 and higher at some. If you don't meet low doc criteria, lite doc uses BAS or bank statements instead.
Yes, if you have an ABN and the equipment is for business use. We can arrange finance for power tools and workshop gear, trailers, skid steers, mini excavators and similar equipment, new or used, and compare lenders to see who will fund the asset you want. Loans generally start at $10,000, and older or specialist items suit fewer lenders, so tell us what you're buying and we'll confirm before you apply.
Often, yes. Some lenders accept an ABN of a few months with a deposit, and more options open at 12 months and again at 2 years. If you don't have full financials or tax returns, low doc relies on your ID and your own declared income, subject to lender criteria such as ABN and GST age and property or a deposit. If you'd rather show BAS or bank statements, that's lite doc, its own option. Past credit problems narrow the choice but don't always rule you out.
Two quick steps. No impact on your credit score to get a quote.
Greenside Finance Pty Ltd (ABN 76 678 053 122) is an Authorised Credit Representative (#561052) of Fintelligence Pty Ltd, Australian Credit Licence #511803. Unit 5/531 Hay St, Subiaco WA 6008 · 1800 147 336. All finance is subject to lender approval, terms, conditions and fees. Information on this page is general and doesn't consider your objectives, financial situation or needs.

