
Perth-based · 40+ lenders · Australia-wide
Greenside Finance team · Updated October 2026
Finance for new or used excavators and earthmoving machines, for owner-operators and contractors. A Perth broker compares 40+ lenders, Australia-wide.
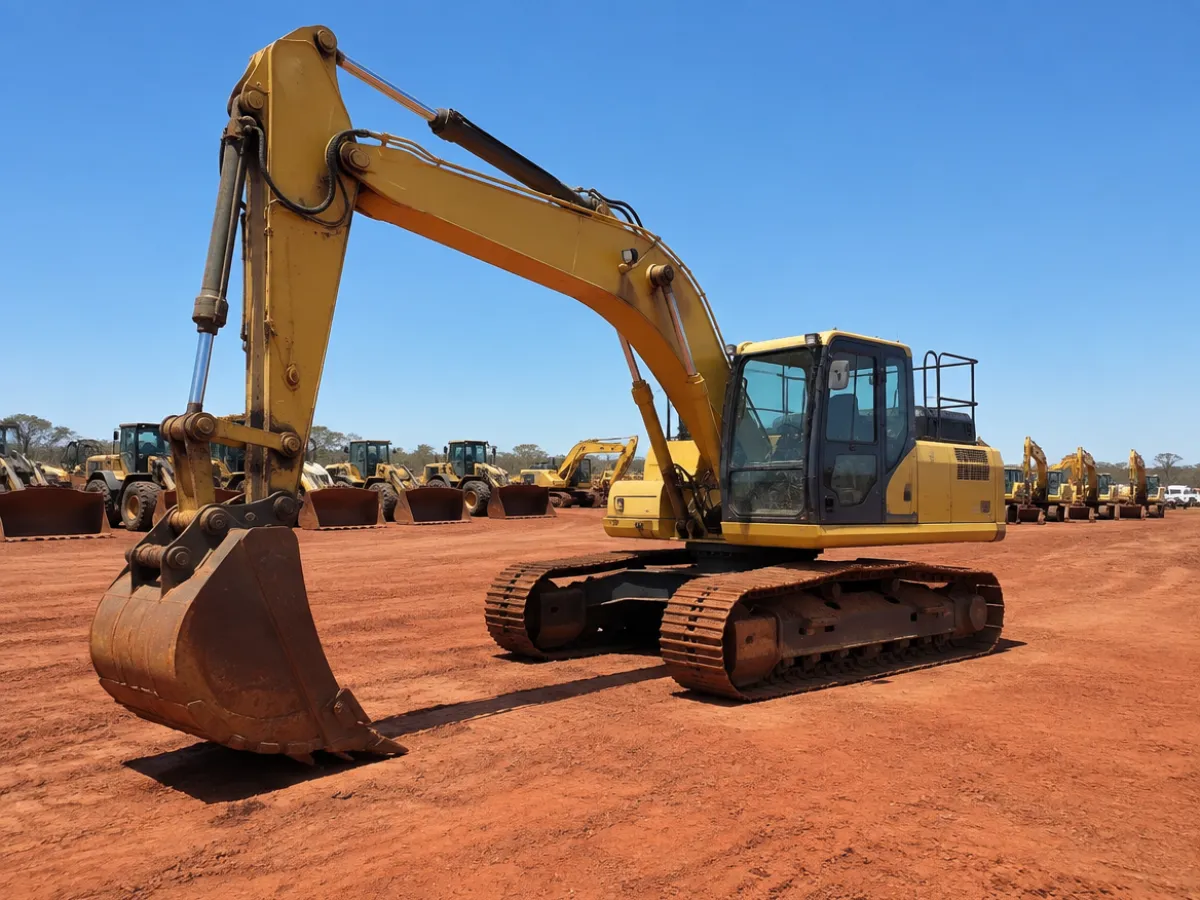
Excavator finance is a business loan, usually a chattel mortgage or lease, for a new or used excavator or other earthmoving equipment, with the machine as security. Greenside Finance arranges it across Western Australia for machines bought from a dealer, at auction or from another business. We're Perth-based finance brokers comparing 40+ lenders for owner-operators, civil contractors and Pilbara and Goldfields crews, lending Australia-wide.
Other machinery? See equipment finance.
| Factor | What it means for you |
|---|---|
| ABN and GST age | Some lenders take a new ABN with industry experience and a deposit. More open up at 12 months; the widest choice is around 2 years of ABN and 1–3 years of GST. |
| Property | Owning property is the biggest lever for no-deposit and low doc approvals. |
| Deposit | Without property, many lenders want 10–20% as cash or a trade-in machine. |
| Machine age and hours | Many lenders fund earthmoving gear to around 15–25 years old at the end of the loan. Older or high-hour machines may need a valuation or a shorter term. |
| Industry | Machines on mine sites are fine at most lenders, but some are cautious with businesses earning mainly from mining. We match you to lenders comfortable with your work. |
| Income pattern | Contract and seasonal income is normal. Bank statements and a contract or forward work list explain gaps such as the northern wet season. |
| Credit | A good credit history opens the panel. Defaults narrow it. |
Plenty of WA machines change hands at auction, online, or between contractors. Most lenders fund these, though some price private sales higher.
Low doc:
Lite doc (easy doc or mid doc): recent BAS or business bank statements instead of tax returns, for operators who don't meet low doc criteria.
Full doc: two years of tax returns or financials and ATO notices of assessment.
Low doc suits established operators (usually 2+ years of ABN, GST-registered, ideally owning property) whose tax returns aren't current: the lender relies on your declared income. Lite doc uses BAS or bank statements and suits newer ABNs or non-owners. Full doc suits larger fleets and bigger single machines. Rates depend on the lender and your profile; low doc is often priced the same as full doc for established businesses. More: low doc loans.
Real client example. Details changed to protect privacy. A drainage contractor bought two excavators from another business, company to company. The PPSR showed both still carried the manufacturer's finance. We started the discharge with the manufacturer's finance arm the day the deal was quoted and arranged a statutory declaration with remote witnessing. The lender settled once the discharge was in hand.
Yes. Most lenders fund auction purchases. Get pre-approved before the sale and send us the docket and serial number straight after.
Often, yes. Many lenders fund earthmoving equipment up to around 15–25 years old at the end of the loan. Older or high-hour machines may need a valuation or a shorter term.
Yes, if they're bought with the machine and listed on the invoice. Buckets, hitches, breakers and augers are common.
Some lenders will, especially if you've operated machines as an employee before. Expect a deposit or property backing, and fewer choices until your ABN reaches 12–24 months.
Often, yes. We apply to a lender for pre-approval to a set limit, so if it's approved you bid knowing your ceiling. The lender confirms the machine after the sale.
Property owners with an established ABN often don't. Without property, many lenders want 10–20% in cash or trade-in.
No, but it needs time. We find every registered interest on the PPSR and arrange the discharge before settlement. Start early: discharges can take days.
Two quick steps. No impact on your credit score to get a quote.
Greenside Finance Pty Ltd (ABN 76 678 053 122) is an Authorised Credit Representative (#561052) of Fintelligence Pty Ltd, Australian Credit Licence #511803. Unit 5/531 Hay St, Subiaco WA 6008 · 1800 147 336. All finance is subject to lender approval, terms, conditions and fees. Information on this page is general and doesn't consider your objectives, financial situation or needs.

